Showing posts with label economics. Show all posts

5/29/2023

GloboMMT

Thought I’d check in after 5 years of hibernation. It’s been a remarkable run, right? Fear of a virus is racist, no wait it’s actually a global pandemic, J6, Russia invading Ukraine after apparently consulting a Magic 8 Ball, Epstein doing something or other with somebody or other, Twitter hating Musk so much that the company sued Musk in court to force him to buy it, the rise of Greta, the fall of Silicon Valley Bank, the Durham report, whatever Bud Light is doing, and so forth.

Except, not. It’s the same soup warmed over. Nothing has fundamentally changed. The world still works the same way it worked previously. Once you see that MMT is the funding mechanism for the global power structure, you can't unsee it. Strange and disconnected phenomena make more sense.


The tl;dr version is this: everybody saying that de-dollarization is imminent, that the petrodollar is the core of the current system, that the BRICS or SCO or whatever alphabet soup geopolitical group are introducing a new international financial system that will radically change global power, has a basic burden of proof to describe what the purported alternative actually is. Boil away the academese and there are only a small handful of choices for a different reserve asset to move away from the imperial quad of USD/GBP/EUR/JPY.


Really just four choices: the Chinese yuan/renminbi as a different national currency, the IMF SDR as basically a more official global union of empire+China, gold (or possibly gold+silver) harkening back to a more physical financial world, or bitcoin (embracing techno utopianism in all its futuristic glory). That’s it. No other concept, commodity, or country (or group of countries) comes close to having the transnational economic clout of DC and Beijing.


(As an aside, if you didn’t know that the Chinese and American currencies have been closely linked for years, stop and think about that. The first thing that an alternative system has to do is break that link…and deal with all the consequences that would occur if the yuan/renminbi actually appreciated meaningfully against the US dollar.)


Russia is the interesting exception that proves the rule, a country big and powerful enough to be mostly independent and yet what that means is Russia has comparatively little integration with the global financial system. As a simple example of scale, the niche blogging company that Sergey (Mikhailovich) Brin, who was born in the USSR (in Moscow no less), co-founded with Larry Page has larger revenue than the volume of trade between Russia and China.


As someone who has found himself at a rather unique intersection of business and public policy, history and current events, critiquing MMT (Modern Monetary Theory) from ‘the left’ rather than ‘the right’, from the perspective of someone who actually believes both parts of that disruptive and increasingly quaint phrase ‘limited government’, I have watched somewhat bemusedly as waves of sensationalist prognostication have crashed on rocks of reality.


One of the ways to rebrand the politicization of fiat currency has been the term multipolarity. Basically, the idea that it’s not just the US national currency that matters, but also national currencies from other important countries around the globe. This is especially popular among English-language commentators who carve out a niche that purportedly critiques US (or ‘Western’) imperialism. Yet coincidentally a common theme amongst them is that they are unable (unwilling?) to address the current economic power base of wealthy and connected insiders or offer a concrete proposal of an alternative international financial system that would actually change anything.


If we are trying to understand what is happening in the world - both for the existential value of truth itself and perhaps also a more practical value of feeling less overwhelmed by a seemingly chaotic world - then realizing that multipolarity is simply another iteration of the longer running MMT fad helps make sense out of that perceived chaos.


The short story is this: MMT/multipolarity defines the existing power structure. It is the funding mechanism that drives every policy American “progressives” and foreign anti-Americans claim to despise so much. It is how governmental and nongovernmental officials coordinate policy all over the planet. Multipolarity is not a change from the current international financial system but rather the continued operation thereof.


Look at who manages the Bank for International Settlements (BIS) and International Monetary Fund (IMF) as of May 2023:


BIS General Manager - Agustín Carstens (Mexico)

BIS Deputy General Manager - Luiz Awazu Pereira da Silva (Brazil)

BIS Secretary General - Monica Ellis (New Zealand)

BIS General Counsel - Diego Davos (Belgium)

BIS Head of Banking - Peter Zöllner (Austria)


IMF Managing Director - Kristalina Georgieva (Bulgaria)

IMF First Deputy Managing Director - Gita Gopinath (India)

IMF Deputy Managing Director - Antoinette Monsio Sayeh (Liberia)

IMF Deputy Managing Director - Kenji Okamura (Japan)

IMF Deputy Managing Director - Bo Li (China)


Not exactly a grouping of ordinary ‘Muricans with high school diplomas from Texas or Appalachia.


Hat tip to CJ Hopkins for inspiration for the title (GloboMMT). He’s been developing an angle on describing our current brand of trending authoritarianism as GloboCap, short for global capitalism. Personally, I think we’re so far removed from capitalism at this point that the word is unhelpful, but Hopkins’s turn of phrase has a lovely overall ring to it. Plus, it centers the reality of global coordination instead of the shell game of national competition.


What follows is my take on a longer version of the story. Buckle up (remember cars?) future archaeologists/alien overlords, it’s a lot to digest. But it’s worth it just in case you read the short story and are intrigued but don’t quite buy it. Or you’re stubborn and want Tom Cruise to yell show me the data a little louder.


For starters, here is a recent event that you can’t make up if you tried. It’s not a big, flashy scandal. Rather, it’s the pedestrian, mundane nature of it that is so illustrative. Leon Botstein, the President of Bard College in New York, Leon Levy Professor in the Arts and Humanities, and Chancellor of the Soros Open Society University Network (OSUN) received $150,000 from deceased pedophile Jeffrey Epstein (). But he only admitted this after the Wall Street Journal found out about it. Before, his story had been that he had solicited money from Epstein but was unsuccessful. Botstein simply forgot $150,000 in payments in 2016.


For any ordinary person, receiving $150,000 in one year from a well-connected financier would be a notable event. That is an amount greater than the entire net worth of the median American family. You’d remember both soliciting and receiving that much money for the rest of your life. But this is so common in higher ed and the world of global power that it is unremarkable to the people involved.


Bard is a particularly intriguing place because it’s both an institution with traditionally liberal/leftist interests and, simultaneously, a place with remarkable coziness with the existing power structure of the international financial system. Located in Annondale-on-Hudson, it’s less than 100 miles from Wall Street. The same Leon Levy whose professorship Botstein holds is also the namesake of the Levy Economics Institute of Bard College. That think tank has attracted arguably the main enclave of American academic MMTers, such as Senior Scholar Larry Randall Wray, Research Scholar Pavlina R. Tcherneva, and Research Associate Stephanie A. Kelton. The Open Society network funded website hosting for much of the University of Missouri - Kansas City’s old Center for Full Employment and Price Stability (UMKC CFEPS) working papers at Bard’s website.


Although interestingly, Wray’s classic - Working Paper 3 - isn’t available for public review at that site.  You have to know it’s from CFEPS and then use the wayback machine at the internet archive to find it. If you’re not an Econ nerd or otherwise familiar with that document, here’s an example of how MMT perpetuates the same assumptions, biases, and systems that the ruling class has used for decades. This quote comes from page 4 of the document published in January of 2000 when Wray (and some other MMTers affiliated with Bard) was at UMKC:


“For the sake of our discussion in this section, we will assume that the government's announced wage (BPSW) is $6.25 per hour…We will also assume that this is a "living" wage…”


One of my favorite jokes about economists from business school was to imagine that you’re marooned on a desert island and you discover a cache with lots of intact canned goods. Yay! Now, how do you open them? If you’re an economist, you assume a can opener.


All joking aside, these are the folks who have been pocketing cushy salaries in academia for decades while demanding that a reserve army of the employed be paid minimum wage using terms like Employer of Last Resort (ELR) and Job Guarantee (JG). In a remarkable coincidence, they don’t want the basic public sector wage to be applied to themselves. Nor do they propose that employees in the various imperial fiefdoms they proclaim to detest so much be paid minimum wage. Those workers, according to MMT, also deserve higher compensation.


To glimpse the story in basic math, as an example Wray was paid a salary of $106,630 by the economics department at UMKC in the 2008-2009 academic year in the heart of the GFC (Global Financial Crisis). According to Social Security Administration data that put Wray at the 94th percentile of all workers in the US economy(!).


MMTers still offer no explanation for why they should be paid so much more than child care workers or home health aides or food service workers or any of the millions of other employees (and prisoners) already making $15/hr (or less) or the potential additional millions they would add to public sector employment - but at a minimum wage, of course, because buffer stocks work so well at containing inflation, after all. Mostly they hope people don’t notice. Sort of like how the President of Bard College didn’t notice when somebody gave him $150,000 for no reason.


Then there’s the more global focused English-language anti-imperialists who don’t actually offer solutions to defund empire. Michael Hudson is a big name in this arena, especially the critique of “finance capitalism” as if finance is the only industry that’s bloated and predatory or that anything about global finance resembles market-based economics. He has spent decades generically decrying imperialism yet declines to offer concrete proposals for what areas of government spending and regulation he would actually cut.


As a concrete example, following are the approximate sizes of various parts of the official US economy (what’s captured by GDP, which of course is itself a flawed metric):


$1.3 trillion - financial services and insurance

$1.4 trillion - intellectual property

$1.9 trillion - nonprofit institutions

$2.2 trillion - durable goods

$2.5 trillion - food (combined on and off-premise categories)

$2.5 trillion - nondurable goods (excluding food)

$2.7 trillion - health care

$3.0 trillion - housing and utilities

$4.4 trillion - government (consumption and investment)


How can one look at that list and conclude that financial services is a unique problem in the economy, that the US doesn’t make anything anymore, or that the core macroeconomic problem is a lack of socialism because we don’t spend enough currency units on government? The numbers simply don’t tell that story. The story isn’t about aggregates, it’s about how we spend currency units. What do we get for the money?


Another great source of purportedly anti-imperialist multipolarity commentary is authors like Pepe Escobar at The Cradle. Shortly after the Russian SMO (special military operation) in the Ukraine in early 2022, Escobar excitedly posted about the game-changing nature of Russian gold, Chinese petroyuan, and Sino-Russian coordination to circumvent the US dollar:


“The Eurasian system will be based on “a new international currency,” most probably with the yuan as reference, calculated as an index of the national currencies of the participating countries, as well as commodity prices. The first draft will be already discussed by the end of the month.”


Except, not. Here we are 14 months later. There is no new international currency. And that notion of an index of participating countries and commodity prices is gobbledegook. An index of multiple national fiat currencies is an even more unstable concoction than using a single currency.


The Chinese ruling class, like they have done for decades, continues to partner with the ‘Western’ ruling class. There is far more alignment than disagreement between ‘the West’ and ‘the East’. Larry Fink, CEO of Blackrock (the asset management company that owns lots of proxy voting shares in all the other transnational companies that the multipolarists claim to decry), was not only allowed to visit China but was allowed to leave the country without arrest. More broadly, China has not issued an arrest warrant for a single major financial fraudster or war criminal from corporate executives to government officials to billionaire oligarchs. And here we are in 2023, and the Chinese yuan (and Hong Kong dollar) are still linked to the USD.


To critique empire, you have to offer an alternative. And the folks stuck in an MMT framework can’t (won’t?) extricate themselves from that framework. So here I am, as anti-imperialist as the next guy, yet paradoxically quite bullish on American empire for the foreseeable future based upon how the past five years have unfolded. Because even the multipolarity advocates who claim to dislike the current global power structure of the past 6+ decades can’t actually bring themselves to abandon it. As a systems thinker, that unwillingness to walk away from a system you don’t like fascinates me.


It’s like when retailers such as Walmart and Target created CurrentC and bad-mouthed the credit card companies. Yet they refused to take the obvious step of actually walking away from credit cards, continuing to allow customers to use them for payment throughout the comically absurd lifetime of the Merchant Customer Exchange.


That’s how powerful the current international financial system is. China isn’t doing what Hudson and Escobar and others say they want of creating a new system. Instead, China has spent considerable energy integrating into the existing global system, partnering with the BIS and working with the UN system of institutions including central players like the World Health Organization (WHO), joining the IMF SDR currency basket, and advocating for the UN Sustainable Development Goals (SDGs - a/k/a Agenda 2030). So long as Beijing and DC work together, there is no individual country or regional bloc that has meaningful influence to do anything about it.


You don’t need hippie tree-hugger perspectives to see it, by the way. Simply take publicly available data from the heart of the power structure, the CIA’s World Factbook.


If you break the world up into regional blocs, what becomes clear upon examination of the data is that South America, Sub-Saharan Africa, and the Indian Subcontinent (Greater India or South Asia or other preferred description for the area between SE Asia and West Asia) make up a large part of global population yet a small part of global finance*. In contrast, the empire+China accounts for approximately 66% of global GDP. Also 71% of global gold reserves and 100% of the IMF’s SDR basket. Think about that last one for a minute if you didn’t know that particular factoid.


Some time in the future, will the yuan and dollar float (or disappear) rather than being linked? Will China officially claim much larger gold reserves, or alternately, claim that empire doesn’t have the gold reserves it claims to have? Of course. But that’s a bit like pointing out that in the future, the continents as we know them today will collide again, swallowing up some oceans and creating others.


So, back to hibernation for another few years. Although, do wake me up if MMT/multipolarity/anti-imperialists explain what exactly the new global financial system is going to be and when it will arrive. Because this article from Escobar from April of last year typical of the de-dollarization hype hasn’t aged well, unless one defines ‘soon’ on geological time scales:


“You are at the forefront of a game-changing geo-economic development: the design of a new monetary/financial system via an association between the EAEU and China, bypassing the US dollar, with a draft soon to be concluded.”


*Update: Thought I'd post the numbers behind this for handy reference over time. CIA World Factbook data in GDP at Purchasing Power Parity (PPP) in constant 2017 dollars. IMF SDR basket as of 2022 weighted percentages. Regions are my categorization. EEZ is exclusive economic zone (waters outside national territory to which nations have certain economic rights). Gold ounces are the internationally claimed official reserves converted to troy ounces (it's all secret, so who knows of course what the actual numbers are, but until another nation challenges the figure, the official figure is the figure). Empire (the 'West' or 'NATO & Friends' or the 'Golden Billion' or whatever) is the sum of the first three groups. To make everybody super happy, I conveniently split the Ukraine 50/50 between Non-Russian Europe and Greater Russia. Three minor blocs are not listed here (Central America, Oceania, and Non-Imperial Lands, a sort of none-of-the-above for surrounded countries like North Korea).

Imperial Lands is the one non-geographic bloc. It's all the countries that would fit in a regional bloc but are more connected to an imperial institution instead. For example, Turkey one day in the future might have a serious enough dispute with Greece specifically, or Europe generally, that drives them from NATO. But until that day, Turkey isn't merely a minor periphery of empire pulled more to West Asia. Rather, it's been a member of NATO for 7+ decades, has NATO's second largest army, and houses facilities like Incirlik and land command.

NAFTA

  • GDP - $25.4 trillion
  • Geographic area - 21.8 million sq km
  • EEZ - 20.2 million sq km
  • Gold - 265.4 million ounces
  • IMF SDR - 43.4%
Non-Russian Europe
  • GDP - $24.4 trillion
  • Geographic area - 5.6 million sq km
  • EEZ - 29.3 million sq km
  • Gold - 397.3 million ounces
  • IMF SDR - 36.7%
Imperial Lands
  • GDP - $13.3 trillion
  • Geographic area - 11.5 million sq km
  • EEZ - 20.8 million sq km
  • Gold - 59.5 million ounces
  • IMF SDR - 7.6%
Greater China

  • GDP - $25.4 trillion
  • Geographic area - 9.6 million sq km
  • EEZ - 0.9 million sq km
  • Gold - 64.7 million ounces
  • IMF SDR - 12.3%
Greater Russia
  • GDP - $5.4 trillion
  • Geographic area - 21.2 million sq km
  • EEZ - 7.6 million sq km
  • Gold - 100.6 million ounces
  • IMF SDR - 0%
Greater India
  • GDP - $11.9 trillion
  • Geographic area - 4.5 million sq km
  • EEZ - 4.2 million sq km
  • Gold - 28.1 million ounces
  • IMF SDR - 0%
Southeast Asia
  • GDP - $8.3 trillion
  • Geographic area - 4.5 million sq km
  • EEZ - 9.5 million sq km
  • Gold - 23.6 million ounces
  • IMF SDR - 0%
West Asia & North Africa
  • GDP - $7.7 trillion
  • Geographic area - 4.5 million sq km
  • EEZ - 12.8 million sq km
  • Gold - 49.1 million ounces
  • IMF SDR - 0%
Sub-Saharan Africa
  • GDP - $4.4 trillion
  • Geographic area - 24.3 million sq km
  • EEZ - 11.7 million sq km
  • Gold - 5.6 million ounces
  • IMF SDR - 0%
South America
  • GDP - $6.5 trillion
  • Geographic area - 17.7 million sq km
  • EEZ - 12.3 million sq km
  • Gold - 15.4 million ounces
  • IMF SDR - 0%

Update 2: Over the past month there have been some great examples of the difference between the hype and the reality that is easier to see and understand once you see GloboMMT at work. Is it possible, theoretically, that the global power structure will radically change this summer? Of course, but it's highly unlikely given the incentives and relationships at play.

On the hype side, Pepe Escobar got all excited that in St Petersburg (an interesting international conference but one that has zero policy impact on global power/finance and is so deep in the globalism that in 2023 they still require healthy attendees to get COVID tests)

"...the world's new powers gather to upend the US-concocted rules based order..."

while Jim Rickards is getting even more excited about a BRICS meeting in August where, supposedly:

"This will be the biggest upheaval in international finance since 1971. It's taking direct aim at the dollar."

Contrast that with the reality of transnational public/private coordination where the head of state of China met with some random private citizen by the name of William or something while the IMF pontificates to African central bankers about yet more global alignment rather than pesky sovereign nations proposing their own sovereign things.

1/19/2015

Current Limits of Modern Money (MMT)

Two years where nothing has happened.

That's sort of what it feels like, a brief microcosm of Francis Fukuyama's End of History. What was silly about that was the permanence of the sentiment, this notion that This Time Is Different, but there's a lot of truth to temporary periods of stagnation. It's not that there aren't things happening at an individual level, it's just that the details are all that differ. The same soup warmed over just keeps happening, like we're stuck in a holding pattern waiting for reality to do its thing to unsustainable arrangements.

I haven't even logged into the blog in a while, and I was surprised to find that according to Google's analytics, they send traffic here from time to time, my little personal journal that hasn't seen a new article since before Stephen Colbert decided to go get a real job. 145 links last month? Wow.

So you're reading a bit of an intro or disclaimer I normally don't provide on my thoughts here just in case my little ramblings get picked up by the Google Magic Machine and transported across spacetime. Especially given the recent case study of Marco Ament whereby legitimate and thoughtful criticism was twisted into a variety of things it was not. I don't embrace the conservative takeover of America, the radical right, whatever we want to call it. I believe in market-based economics, not fascism (or communism, for that matter). I'm centrist for a Millennial, but I'm pretty far to the 'left' as far as the general American public goes.

However, I disagree with some of the ways that leftist thought leaders, we might say, have been trying to counter the changes in American political economy over the past half century generally and the past couple decades in particular. What I see is a blindness, an ignorance, almost willfully so, to cast aside or under appreciate how some ideas can be so easily twisted to serve the authoritarian purposes that have been undermining Constitutional governance and creating a dangerously high level of concentration of wealth and power. MLK laid out the clear connection of class that still hasn't fully permeated upper middle class, educated thinking, in tying together racism, militarism, and economic injustice. It's one of the reasons I think of this on MLK weekend. Selma - seriously, go see the movie if you at all have any interest in movies - is so far away, yet so close to home. The two-tiered justice system isn't a relic of the past. Young black men are victims of systemic targeting by our legal system today.

If anything, things are trending worse again, not better, since the advances of the 1950s and 1960s. Highly educated liberals - with the fancy degrees and certifications of higher education serving as impressive gate keepers - in the Democratic party control our nation's major cities, and that is ground zero of much of the oppression and injustice and preventable suffering in contemporary America. It should be neither controversial nor shocking to express such a sentiment, but yet, sometimes it is. The Republicans are not the problem. Conservatives are not the problem. Racists are not the problem. Evangelical Christians are not the problem. Libertarians are not the problem. Gold bugs are not the problem.

We all are the problem. It is an American problem we face, a time to answer again for our era what exactly we mean by created equal, by a more perfect union, by liberty and justice for all.

There's also an interesting personal angle to me for MMT. Growing up in KC, where UMKC hosts the Center for Full Employment and Price Stability, MMT has a bit of a home town feel to it. And there's the interesting related but different approach between business and economics. The business student is interested in what works, in implementation, in how to put things in practice. It is focused and driven by results, by outcomes, by the meaning of what is accomplished. But MMT comes out of the more academic side of theorizing and a bit of the math and physics envy that plagues the social sciences generally and economics in particular. That's a personal connection for me especially since one of Professor Randy Wray's major influences was Professor Hyman Minsky, a long time academic in the economics department at Washington University in St. Louis. One of my most memorable interactions with econ professors was at Washington University when Professor Murray Weidenbaum, who passed away this spring, spoke in our Honors in Management seminar about government regulation and so forth. A business student asked him what he thought of one of the big contemporary issues of the day - Enron - and the gist of his answer was that mistakes probably were made but it didn't amount to fraud. That unwillingness to call a spade a spade, to name crime as such, caught my attention then and I continue to see it today, across a wide swath of political rhetoric and intellectual frameworks. It's almost like explaining the past couple decades as a pedestrian crime wave committed by a bunch of run-of-the-mill criminals rather than some complicated phenomenon by SuperSmart People implicates everyone whose reputation is tied up in our system, from corporate executives to Democratic politicians to tenured professors to police chiefs to prosecutors to judges.

Saint Louis County Prosecutor Bob McCulloch isn't some outstate Republican with no education beyond high school, nor is he some crazy right-wing economist or pundit. He's a white upper middle class Democrat with an advanced degree. And what is notable about his conduct is not that it was outside the mainstream. Rather, what is notable is that he is very representative of the two-tiered justice system. Hard prosecution of petty crimes allegedly committed by people in poverty combined with light prosecution of serious crimes allegedly committed by armed government employees, big time financial fraudsters, and so forth. And lest anyone in the heart of the problem, the NYC-DC nexus, think this is a flyover state problem, that canard is unfortunately put to rest quite easily.

What follows is very specifically my perspective on current limitations in modern money. It is very specifically framed that way because I don't think the whole thing is simply bunk, nor do I think it is impossible to address these matters. Rather, what I am pointing out is that this perspective is currently limited, as if admiring a beautiful landscape by holding a hand over one eye. So far I have been rather personal and vague. One of the core challenges of discussing modern money in detail for critical analysis is that the details differ from one proponent to the next. There is no periodic table of the elements or constant speed of light to serve as base and reference point.

So I'm going to summarize four key points of MMT as I would describe and synthesize them:

1) MMT observes that good monetary policy must utilize a buffer stock policy. In other words, there must be some price anchor attached to a fiat currency issued by a sovereign government. The government can of course create as many currency units as it wants, but this must be checked by that price anchor. Some of the most common such buffer stocks are gold, unemployment, and full employment (AKA ELR, AKA JG - a job guarantee, the acronym I'll use from here on out for simplicity sake). But the key here is that just about anything can be argued to serve this purpose in theory, from silver and copper to wheat and soybeans.

2) MMT observes that, since we have to choose a buffer stock, we should choose the best one. The best one is full employment (JG).

3) MMT observes that not only does JG serve a monetary function, it also solves non-monetary problems. Unemployment, homelessness, poverty, inadequate healthcare, skill deficiencies, etc. Giving people a job gives people access to overcoming these barriers. In short, work in the formal economy is valuable in and of itself, not just for the income such employment provides.

4) MMT observes, at least in some circles, that balanced budgets are inherently bad. In other words, it's not just that the government can run a deficit, but more than that, that the government ought to run a deficit. Not over short or temporary periods of time, but forever. I will generally refer to this as net deficit spending (i.e., where spending - the creation of currency units - exceeds taxation - the destruction of currency units).

What is immediately obvious and troublesome to me is that points 1 and 2 are closely linked. There is a clear line of thought connecting those two claims. But 3 and 4 are independent. This is not an abstract or theoretical problem. One of the major issues in the labor market is that there are millions upon millions of jobs that have low wages and poor working conditions. We also know that Americans work far more than our peers in other industrialized nations. And finally, we know that single-income households (breadwinners) are more stable than households where all adults must work. Meanwhile on item 4, one of the major issues in government budgeting is that we are already running massive deficits, right now. The Reagan-Bush-Obama era, in fact, is defined in some ways by consistently spending far more dollars than are raised through taxation. In a very real sense, MMT seems easily used to augment the authoritarianism, not reject it.

This post is also titled current limits because it is not that MMT provides poor responses to critiques of the JG so much as it refuses to consider some kinds of criticism at all. For example, Professor Wray explained his thinking in the following manner:

“I’m not going to say more about these final two arguments against full employment as I’m convinced both are fallacious, and because neither of these critiques offers a price-stabilizing anchor for the currency in place of the JG/ELR.”

In other words, MMT does not explain why philosophical and practical objections to JG are incorrect. Rather, the theory handles disagreement by defining it as fallacious and lacking a price anchor. In other words, MMT is aimed at people operating within the mainstream of economics, those that accept point 1 above. So far, it does not appear interested in perspectives that are outside of this mainstream view.

Below, I present three Ps, if you will, that offer different perspectives or insights into the problems posed by JG. In summary, they are philosophical, practical, and political.

On the philosophical front, JG theorizes that idleness is bad. It asserts, by definition, that time spent employed in the formal economy is necessarily better than time spent doing something else. On the practical front, I present a comparison between the actual functioning of two parts of the government – the Social Security Administration and the National Security State. If one views the situation from a different perspective, it appears clear that social insurance, in practice, works much better than direct employment. Finally, there is a political point worth considering that social insurance has proven its staying power within the confines of the acceptable range of policy options available in US culture. A JG, in contrast, has never been tried. The most expansive programs we have, like the WPA or the Vietnam War, have either been temporary or controversial (or both).

For me, the unwillingness to defend philosophical objections to JG is the most powerful indictment of the current limitations of theory built around modern money. It demonstrates either a tremendous lack of understanding about the core assumptions and values that one brings to political economy, or, a lack of intellectual seriousness and rigor. Formal employment is inherently authoritarian. That’s the point – one person hires another person to do what he or she says to do. This can work very well in a system of equality and rule of law where employees and employers form consenting agreements to produce a valuable outcome.

However, the inherent dangers of centralized power should not be taken lightly. Slavery, indentured servitude, physically abusive working conditions (“sweatshop labor”), theft, discrimination, harassment, and child labor are some of the more commonly understood problems of too much unchecked authority. It is easy to rationalize away the oppressive nature of work as something that is in the past. But it’s not. More human beings are enslaved today than in the 19th century, from domestic servants to children caught up in sex trafficking.

The authoritarianism of the workplace is prevalent in less extreme cases, too. There is a direct link between stress of overworked employees and mental and physical health problems. Indeed, the trauma inflicted by workplaces where employees have little power is eerily reminiscent of the description that Wray himself offers of the problems of unemployment:

“…divorce, deteriorating physical and mental health, abuse of children and spouses, gang activity, and crime.”

How the JG works isn’t the only issue. There is also the matter of what the JG will accomplish. It is a rather dull and depressing view of humanity to posit that human beings are only properly motivated and organized when employed. Formal employment can be good. That does not mean it is necessarily good.

Indeed, the exact opposite approach would seem most in line with human progress and civilization. It is the productivity of agriculture and commerce and so forth over the years that allowed people to pursue higher callings in the arts and sciences. Our curiosity and creativity as a species requires rest and idleness and leisure and spontaneity and failure; the very opposite traits maximized by employment-based resource allocation. It is better for the government to pay someone to pursue their own hobby than for the government to pay someone to do work that is of little interest or value. The range of activities that humans engage in outside of formal employment is as vast as the imagination, from very obvious pursuits like parenting and volunteering and civic engagement to more particular passions such as a faith community or visiting relatives or painting or singing in a choir or going hiking or running for school board or coaching a little league team or exploring the stars or writing a novel or any other myriad of such activities.

Finally, JG inherently sidesteps the issue of inequality. Excessive inequality is one of the core problems facing our society. JG entrenches inequality in a system where some people have ‘good’ jobs that pay much more than the compensation earned by the less fortunate workers stuck in the JG positions. The trick is that the higher one sets the minimum bar of wages, the more employment then shifts from the private sector to the government. It is a dynamic variable, not a static constant. It’s not just the 10 million people who are unemployed.

80 million workers make less than $30,000 a year(!). Does MMT really propose that the government hire that many people? How about the 100 million workers who earn less than $40,000? And what about the other 90 million adult Americans who aren’t in the labor force at all? Why not just increase the minimum wage and taxes on the wealthy instead of all the effort involved in being an employer of last resort?

The government's own data shows quite clearly that some workers make far more than even $40K a year. The 'mean annualized wages' for an economics professor is $100K! Health profs make $106K. For legal profs, it's $122K. These are massive wage differentials amongst workers whose jobs are based upon government policy, not private sector employment.

That doesn’t mean that critiques of how and what the JG accomplishes are necessarily right. But it certainly demonstrates that JG proponents must defend it on these grounds if they wish for those of a different perspective to take the JG seriously.

If the above discussion is too heady or vague for your taste, then let’s turn our attention to practical concerns. I will characterize these in two ways – first, concern about the efficiency of the price anchor, and second, concern about the projects a JG would pursue.

I fundamentally reject point 1 above, the MMT notion that a system of political economy must choose some sort of buffer stock to serve as a price anchor for the state’s currency. Quite simply, I would suggest that price anchors don’t work. Thus, they are irrelevant. Whether it’s hard money like gold, silver, copper, iron, wheat, corn, or some other physical commodity, or fixed foreign exchange rates, or unemployment, or full employment, there is simply no theoretical or historical record of price anchors actually preventing a political system from spending whatever currency units it desires. After all, that’s the point of fiat currency – issuance is dictated by the government. This is what makes freely floating exchange rates so valuable! What matters is not the price of resources. Rather, what matters is the distribution of those resources. In other words, inflation is managed by the denominator (the productive wealth of society) not the numerator (the currency supply). Taxation, rule of law, floating exchange rates, in short, the checks and balances of Constitutional government, is what serves as the 'buffer stock'. That these are external constraints to the monetary system is a feature, not a bug.

But for the sake of argument, let’s say that you do have to choose some specific mechanism to buffer currency issuance. Once we actually analyze government employment, it becomes painfully obvious that direct employment is a very inefficient mechanism for handling money.

The Social Security Administration employs about 65,000 people. In contrast, the National Security State employs about 4 million people (exact numbers here are of course difficult since the thing is so big and secretive that no one knows exactly how big and secretive it is). Why compare two parts of the government that have such wildly different employment levels? Because they spend almost the same number of dollars into the economy.

Think about that for a second.

The OASI and DI trust funds of the Social Security Act together accounted for about $823 billion in spending last year. The actual direct costs of the National Security State (discretionary security plus war on terror) were about $811 billion in 2012. That’s a remarkably similar amount of monetary impact for two very different employment levels.

In other words, each Social Security employee generated about $12 million of “monetary work”. A National Security State employee, however, only generated about $200,000! To say that differently, one social insurance employee generated the same price anchor effect of 60 direct employees. If we truly want a system with an effective price anchor, social insurance is the way to go. Benefit payments are much easier to tweak than employment levels.

But the problems with the National Security State are not confined to it being an inefficient spender of dollars (ha, think about that one for a second!). There are a whole range of indirect costs incurred by the National Security State that do not happen with social insurance that I will cover below in the third part about politics. But before getting to that, the other practical problem is how many more projects of the same size we will have to create and manage. This gives us a handy unit of measure in our ballpark estimate: 4 million jobs = 1 NSS.

So in order to implement JG, we would have to create 5 new projects of the size of the National Security State if 20 million people signed up. If 40 million people signed up, we’d have to create 10 new projects. If 80 million people signed up, that would be 20 NSS! Our system has trouble managing 1 NSS project. How exactly could it manage even 2 or 3 of them, let alone 5 or 10? Those details are critically important to any serious policy proposal that the government guarantee a job to everyone who wants one.

Lastly, we come to the political problem with JG. Quite simply, JG is untested. Sure, there have been specific instances where the government has hired a bunch of people. But such systems have never been guaranteed employment, they have never been local employment, and they have never been permanent employment.

This is perhaps the biggest elephant in the room when MMT discusses government employment projects. These projects are only successful when the political process desires to use workers to invest in the public commons, to produce an output that increases the productive wealth of the nation. When the political process has other motives, then we see the terrible consequences that manifest themselves, from waste and corruption to environmental destruction to sexual harassment and discrimination to prisoner abuse to undermining of Constitutional rights. The extreme growth of the National Security State poses a direct threat to the Republic. Constitutional governance is withering away, especially in the “post-9/11” era. MMT assumes good political stewardship when it is precisely a political crisis that confronts us.


In short, we have a management problem, not a monetary problem. That’s the sound bite version for what is currently lacking with MMT analysis – it is a set of policy prescriptions chasing the wrong problem. The solution is not to further entrench the employer-based monopoly on living a comfortable and meaningful life. The employment monopoly itself is part of the problem.

2/13/2012

small potatoes

This post attempts to organize some thoughts regarding where we are headed. It's fun when there is a clear vision, but perhaps the most important times for reflection are when things are muddier. Basically, if we can identify unsustainable trends, we can identify sources of change. While the catch is anticipating what exactly that change will be, having some semblance of the terrain is useful.

One of the analytical approaches that interests me is where the tendency toward optimism/pessimism intersects awareness of reality vs. fiction. There is a lot of emphasis in our culture on the first dimension, almost as if being optimistic is more important than being right. Visually, it puts the emphasis like this, on the vertical columns.


However, an attempt to rationally understand the world around us needs to compensate for that natural cognitive fallibility by emphasizing the horizontal.


Truth requires an ability to interpret events both optimistically and pessimistically, to have a vision of what could be yet also a sense of what might go wrong.

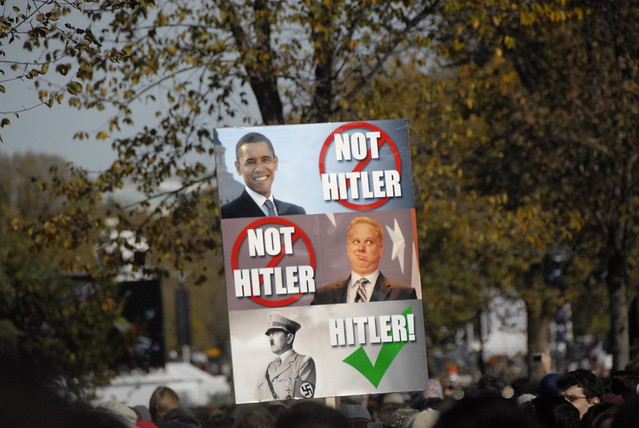
With a couple decades of general wage stagnation providing the context for several years of very specific economic hardship and dislocation, the strategy of the governing coalition of interests in the US appears both clear and consistent. Outside of the national security nexus (GWOT, drug war, deportation, etc.) neither the Bush nor Obama Administrations are particularly hostile toward or directly targeting 'average' Americans. The 'not Hitler' meme was one of the better ones that Jon Stewart and Stephen Colbert encouraged at the Rally to Restore Sanity and/or Fear. Metal Chris captured this one:

Hitler Sign

In other words, it is not so much that individual political leaders act maliciously toward the citizenry so much as they don't care about us. Apathy is the key descriptor; we are simply irrelevant. All of the energy in government is devoted to marshaling whatever resources are necessary to save the Big Fish. What we are left with is the crumbs; small potatoes, so to speak. You can almost see the political class psyching themselves up to sell the latest batch of small potatoes for the masses as something of remotely similar importance to the efforts to save the Masters of the Universe. The transparency that Vice President Biden accidentally showed at the health care press conference, for example, revealed so much.


It's not that Bush's Medicare 'Modernization' or Obama's HCR 'most important reform since FDR nevermind that Medicare thingy in the 60s' are Terrible Legislation that will Destroy America. It's not that Bush was an Idiot or Obama is a Kenyan Muslim Fascist. It's not that abortion and gay rights renders America ungovernable and/or on a path of moral decay and damnation.

Rather, that's not where the action is. Two successive presidents, from two different parties, pushed massively complicated bills that purported to make the healthcare system significantly better. Yet they didn't actually solve the problem of expensive healthcare that causes preventable deaths.

I learned to hone in on that tactic of over-selling and under-delivering as a teenager, and it has proven to be one of the most insightful observations in comparing words and deeds. It's the 'let your yes be yes and no be no' philosophy: either government should do something (such as guarantee quality healthcare for all citizens) or it shouldn't. Both are legitimate beliefs. So is I don't know/let me think about it/it's not important to me. But to pick bits and pieces from both is to give away that neither belief is sincerely held; rather, they are merely justifications for acting upon an unrelated set of beliefs (like the belief that government should protect the economic interests of the wealthy).

Clarity has been particularly revealed with the financial crisis because we now have so much data upon which to draw. It's a simple statement of fact to observe that the Obama Administration supports the use of law enforcement resources to arrest hundreds of thousands of people every year, from illegal drug users to illegal residents to illegal assemblers. Yet one specific group of criminals stand in stark contrast to this massive deployment of police and prisons: politically connected financial crooks. There are literally more baseball players in legal trouble for testimony given before Congress related to steroid usage than there are top corporate executives and board members in legal trouble for all financial crimes combined. The current Secretary of the Treasury was literally head of the New York Federal Reserve when the proverbial bile was impacting the proverbial turbine. The ongoing effort to enter into a mortgage settlement is designed to give the Too Big To Fail financial firms immunity from liability in court - that's the point, that's what a settlement is - a settling of claims of unlawful behavior outside of court.

The preceding paragraph is neither pessimistic nor partisan. It's simply recognizing where we are at. The past and current Presidents of the United States think cocaine users, whistleblowers, protesters, and immigrants should be treated like murderers while financial fraudsters should be treated like people who don't pay a parking meter.

This is beyond specific policy debates or even broad ideological contests. We are now in the realm of questioning, of bringing to light, the core foundations of the American experiment, in all of its grandiose, exciting, and dangerous forms.

Is the Constitution the foundational pillar of secular governance, or do we now look to something else? Is there a rule of law, or a rule by men? Do we want to participate in a peaceful world order, or do we want to instill an American world order? Our basic systems of property and finance and law are quite literally crumbling around us. It's not pessimistic to point this out, to consider the implications. It's responsible.

We know housing prices got out of control. We know higher education costs got out of control. We know healthcare costs got out of control. If actual solutions to these kinds of problems are not going to be forthcoming, that is important to know, to understand what it really means. If you're a Big Fish, you play things very differently, but for areas of American life that depend upon the broad 'middle class', there are only two outcomes. Either public policy ultimately changes and we start encouraging wage growth again (either directly through employment policies or indirectly through additional transfer payments like universal unemployment insurance), or the asset classes dependent upon wages will simply wither away.

This has to happen*.

Either $20,000 - $30,000 a year has to become what it is elsewhere in the world - a comfortable living - or millennials in aggregate looking for jobs have to have a way to earn much more than that in entry level positions. Xers have to have broadly accessible means of earning promotions and switching careers. Baby boomers need to be able to easily replace lost jobs and find part-time income in retirement.

We have utilized credit to bring forward as much consumption as possible. The distant future is finite, too. And the near-future was spent in the past.

Household formation has slowed. New home sales are at record low levels. Record numbers of Americans do not participate in the healthcare system. The percentage of Americans employed has dropped precipitously. Millennials are even ditching things like cable and phones. Student loans - financial commitments undertaken by minors deemed incompetent to buy a Bud Light - can't be discharged in bankruptcy, ever.

Any asset that depends upon middle class wages, any industry that sells to those last marginal dollars of disposable income, will simply shrivel up to a much smaller core.

That's what I don't follow about some of the more intense hyperinflation perspectives. Massive increases in broad pricing measures ultimately requires the government to get money into the pockets of 'normal' people somehow. But that's not the bailout mechanism this time around. The most well connected players are seeing such socialism, but the general citizenry confronts a dearth of capital. I wonder if our 'capitalist' system can handle such misallocation of resources on such a grand scale.

But what I don't wonder is that it is a misallocation. Undermining the rule of law causes many more problems than it solves.

*It is becoming increasingly difficult to get simple, accurate information. The Consumer Price Index, for example, is so watered down and altered that it's not even clear why it's a good measure. A KC strip steak from grass fed open range cattle simply is not substitutable with a breast from a tightly caged, anti-biotically stuffed, corn-fed melange of chickens. Our political process helpfully focuses attention on the relatively small amount of trinkets from places like China and India when the bulk of American household expenses go to much more mundane domestic sources like housing, healthcare, higher education, food, transportation, and so forth. I keep anal financial records, so I thought it interesting to look at a few specific items of my own. By my various calculations, I had a stretch of rental increases that amount to an annualized rate of 4.8%, tuition and fees at Wash U increased by 5%, the cost of an entry level car increased 6%, health insurance increased 12.6%, and food increased 14.7%. The drawback of course is that by being specific, it's unique to me and just anecdotal. But comparing that against the average annual increase in household income over the past decade - 1.6% - it's obvious to see something has to give.

8/04/2011

government by dow 2011

So at work we were discussing some investment things, and it was mentioned that the stock market was down over 4 percent today. That's in one day.

I checked Yahoo Finance just now and yep, it's pretty bad.


'Government by Dow' has been a fun turn of phrase over the past few years, capturing government's capture of the common good by a much narrower set of interests on Wall Street. But when even Wall Street hates your policies, maybe it's time to rethink. Or at least ask, what is going on?

The day the 'grand bargain' a/k/a debt deal a/k/a CYA for cutting popular programs passed the House, the Dow fell from 12144 to 12132. Then on Tuesday, when it passed the Senate and Obama signed it into law, the Dow closed at 11867. Today, the Dow closed at 11384.

In chart form, the past five days look like this:


Wheeeeeeeeeeeeeee.

Enjoy the ride.

But, I know, whocouldanode that idiotic public policy is bad? Or maybe the efficient markets theory is wrong, and The Market isn't right that the debt deal is awful.

Wait, what's that about unstoppable force hitting immovable object again?